
English-speaking accountants in France: Who can legally hold uour accounts ?
Most foreign companies looking for an English-speaking accountant in France ask the wrong question first. The question is not who speaks English. It is who is legally allowed to sign for your accounts.
In France, holding a company's books for a third party is a regulated monopoly. Only an Expert-Comptable registered on the Tableau de l'Ordre des Experts-Comptables may take on the engagement, in their own name and under their own liability. A US CPA, a UK chartered accountant or an offshore bookkeeping provider cannot, whatever their qualification.
Vachon is that registered firm, and it works in English. Founded in 1997 in the 2nd arrondissement of Paris, around 40 professionals, almost exclusively serving foreign-owned French entities.
Not sure your current setup is compliant? A 30-minute call with a partner tells you whether your accounts are held by someone entitled to hold them, and where your exposure sits. No cost, no commitment.

AUDIT
ACCOUNTING

TAXATION
The legal monopoly, in plain terms
The rule comes from Ordonnance n° 45-2138 of 19 September 1945, which created the profession and still governs it.
Article 2 reserves the habitual keeping, review and certification of company accounts to Experts-Comptables.
Article 20 makes it a criminal offence to carry out that work habitually without being registered on the Tableau, in your own name and under your own responsibility.
The offence is punished under articles 433-17 and 433-25 of the Penal Code.
Subcontracting the work to an unregistered provider is caught by the same rule. Registration cannot be borrowed.
What this means for a foreign-owned entity:
Your group's shared service centre may prepare data, but it cannot hold the French engagement.
An unregistered "French accounting service" is not a cheaper option. It is an irregular one, and the exposure lands on your entity.
Your US or UK auditor cannot substitute for the French registration.
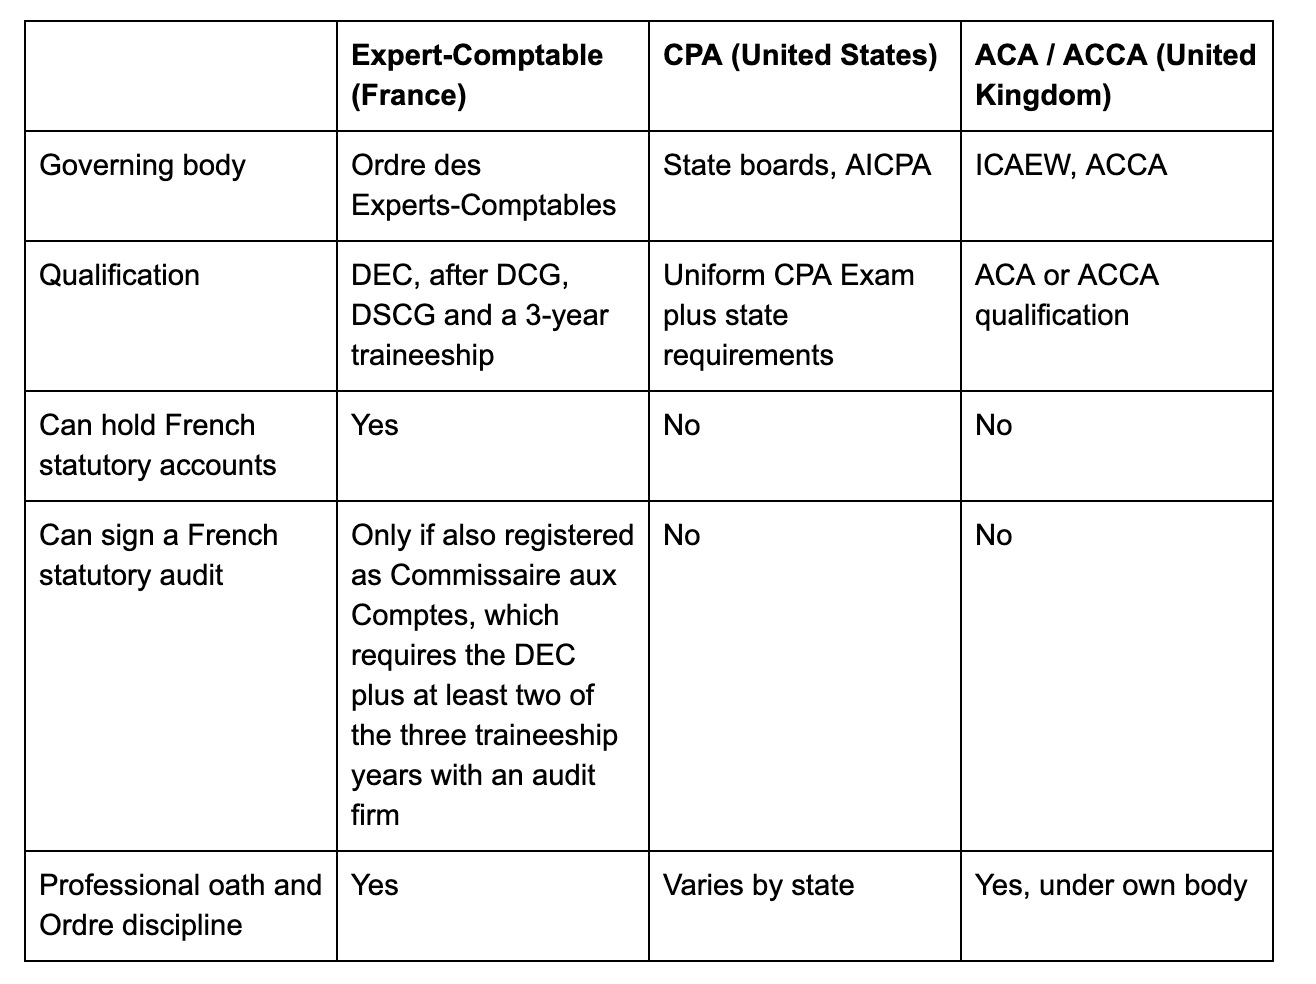
Expert-Comptable, CPA, chartered accountant: what maps to what
The titles are not interchangeable across borders. A firm describing itself as an "anglo-french accountant" is describing its working language and client base, not a recognised French credential. The credential that matters on a French engagement letter is the registration number on the Tableau de l'Ordre.
What a bilingual Expert-Comptable actually delivers
3 blocks, run in French for the authorities and in English for your parent.
Statutory, in French
General ledger under the Plan Comptable Général, with a producible FEC.
Annual accounts filed at the Registre du Commerce et des Sociétés.
Corporate tax return, VAT returns, payroll declarations.
Liaison with the Commissaire aux Comptes where an audit is required.
Group reporting, in English
Monthly or quarterly package mapped to your group chart of accounts.
Reconciliation from French GAAP to US GAAP or IFRS, with the adjustment schedule behind it.
Deferred tax on each adjustment, documented for your group auditor.
Advisory, in whichever language the conversation happens
Entity choice at set-up: SAS, SARL or branch, and the consequences of each.
R&D tax credit claims, transfer pricing documentation.
Permanent establishment exposure when staff work in France.
How to check that your accountant is registered
Four checks, none of which take more than a few minutes. They apply to us as much as to anyone else.
Ask for the firm's registration on the Tableau de l'Ordre des Experts-Comptables, and the regional council (CROEC) it belongs to.
Verify the name on the Ordre's public directory at experts-comptables.fr.
Ask for the lettre de mission. It is mandatory under article 151 of décret n° 2012-432 of 30 March 2012, for every engagement, whatever its size. It must be signed by the registered firm, and it must state the firm's CROEC and its professional liability insurance number.
Ask for the professional liability insurance certificate. Registered firms carry it by obligation. Unregistered providers generally cannot produce one.
If a statutory audit applies, check separately that the auditor is a member of the Compagnie Nationale des Commissaires aux Comptes, a distinct role that cannot be held by the firm preparing the accounts.
A provider that cannot produce the first item is not a provider. A provider that produces no engagement letter is already in breach of the profession's code, before a single entry has been booked.
Already working with someone and unsure? Send us your engagement letter. We will tell you in one email whether the setup holds, at no charge.
English-speaking accountants in Paris, in person
The firm is at Square Louvois in the 2nd arrondissement, between Bourse and Opéra. Partners meet clients on site, and most foreign-owned entities we serve are headquartered or represented in Paris and the western suburbs
Partner-led engagements, with a named partner on each file.
Meetings in English, documents to the authorities in French.
Same-day answer on scoping questions during French business hours.
For entities based outside Paris, the work runs identically. French filings are centralised online, and the location of your accountant has no bearing on which tax office or Ordre applies.
Who we work with ?
French subsidiaries of US, UK, German, Nordic and Asian groups.
French branches of foreign companies, where branch accounting differs from subsidiary accounting.
Foreign companies with no French entity but French VAT or payroll obligations.
Groups arriving after a problem: a failed reconciliation, a tax inspection, an irregular prior setup.
Frequently asked questions
Can a foreign accountant do my French accounting?
No, not as the holder of the engagement. Under article 20 of the Ordonnance of 19 September 1945, habitually keeping a third party's accounts without being registered on the Tableau de l'Ordre is a criminal offence. A foreign accountant can advise, prepare group figures, or work inside your company as an employee, but cannot hold the French engagement.
Is a French CPA the same as a US CPA?
No. The French equivalent is the Expert-Comptable, holder of the Diplôme d'Expertise Comptable after the DCG, the DSCG and a three-year traineeship. The two qualifications are not mutually recognised. A US CPA practising in France would still need French registration to hold an engagement.
Do I need an accountant if my French subsidiary is dormant?
Yes, in practice. A dormant French entity still files annual accounts at the Registre du Commerce et des Sociétés and a corporate tax return. Failing to file is what triggers the first penalty, not the level of activity.
What is a lettre de mission?
The written engagement contract between an Expert-Comptable and a client, mandatory under article 151 of décret n° 2012-432 of 30 March 2012. It defines the scope, who does what, the fees and the termination terms. Its absence exposes the accountant to disciplinary action before the regional council of the Ordre, and it leaves the client without a contractual basis for recourse.
How are fees set for a foreign-owned French entity?
By the lettre de mission, as a fixed annual fee tied to the scope: number of entries, payroll headcount, VAT regime, reporting frequency and whether a group package is required. Fees are not a percentage of revenue. Any change in scope goes through a signed amendment. A firm that quotes without a scoping call is quoting a number it will revise.
Can one firm handle accounting, tax and payroll together?
Yes, and it removes the reconciliation gaps that appear when the three are split across providers. The statutory audit is the exception: independence rules prevent the same firm from auditing accounts it has prepared.