
French GAAP vs US GAAP vs IFRS: The differences table for French subsidiaries
Your French subsidiary files one set of accounts in France and sends another to the parent. When the two stop agreeing, it surfaces at the worst moment: during the group audit, with a bridge that will not tie and nobody able to explain why.
French GAAP is the Plan Comptable Général (PCG), the accounting framework issued by the Autorité des Normes Comptables. Every entity established in France keeps its statutory books under the PCG, in French, in euros, whatever framework its parent reports under. US GAAP and IFRS never replace it. They sit on top, reached through a reconciliation.
Vachon prepares both sets of figures for foreign-owned French entities: the statutory accounts under the PCG, and the reporting package your parent consolidates. One firm, one ledger, one bridge that holds up in audit.
Is your French reporting exposed? A 30-minute review with a partner tells you whether your accounts, your mapping and your adjustments hold together. No cost, no commitment.
Book a reconciliation review →
Below, the three frameworks compared difference by difference, with the PCG article behind each one. Reviewed against the PCG applicable from 1 January 2026.
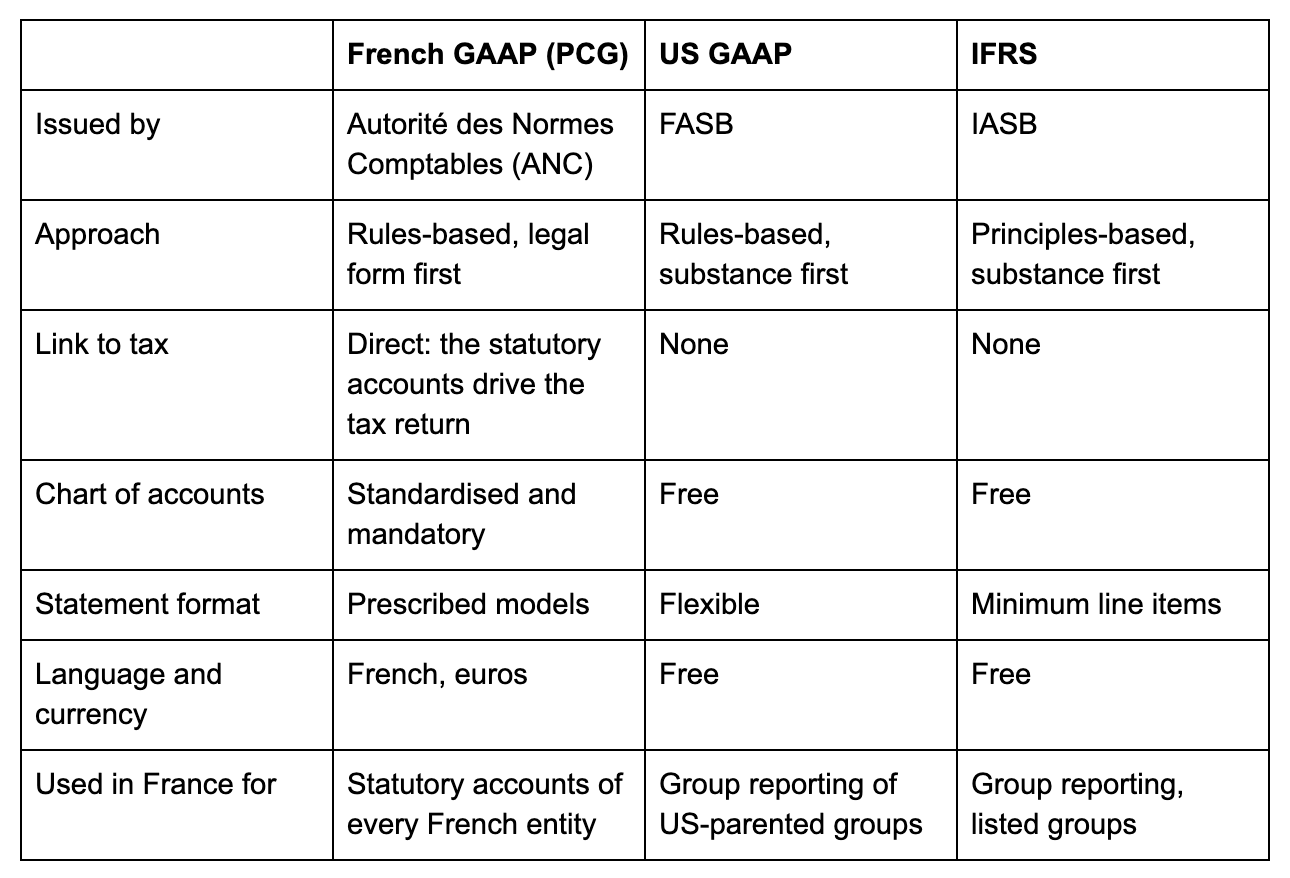
The 3 frameworks side by side
The 8 differences, with the rule behind each
1. Development costs
French GAAP: capitalisation is the reference method under PCG article 212-3, subject to six criteria. Amortised over the project's useful life, capped at 5 years where that life is not reliably determinable (article 214-3). Research costs always expensed.
US GAAP: ASC 730 expenses all R&D as incurred. No capitalisation of internally generated R&D, except narrow software carve-outs (ASC 350-40, ASC 985-20).
IFRS: IAS 38 makes capitalisation mandatory once criteria are met.
Adjustment: reverse the French asset and its amortisation toward US GAAP. Treatments converge toward IFRS.
Most English-language guides state this difference backwards. French GAAP is the permissive framework here, US GAAP the restrictive one.
2. Goodwill and fonds commercial
French GAAP: the fonds commercial is presumed to have an unlimited useful life and is not amortised, with an annual impairment test. Amortised only where the useful life is limited, or over 10 years if that life is not reliably determinable (article 214-3). Small entities may elect 10-year amortisation.
US GAAP: no amortisation for public entities, impairment testing. Private companies may elect amortisation.
IFRS: IAS 36 prohibits amortisation.
Adjustment: arises only where the French entity amortises.
Sources stating that French GAAP always amortises goodwill describe the rules in force before regulation ANC 2015-06.
3. Leases
French GAAP: operating leases stay off balance sheet. The rental is an expense in account class 6.
US GAAP: ASC 842 recognises a right-of-use asset and lease liability.
IFRS: IFRS 16 does the same, with a different expense profile from ASC 842.
Adjustment: usually the largest single item, cascading into depreciation, interest and deferred tax.
4. Retirement benefit obligations
French GAAP: indemnités de fin de carrière may be disclosed in the notes rather than provisioned. Provisioning is the reference method.
US GAAP: ASC 715 requires recognition.
IFRS: IAS 19 requires recognition with actuarial valuation.
Adjustment: book the provision and its actuarial movement each period.
5. Provisions
French GAAP: broader, prudence-driven recognition.
US GAAP: ASC 450, probable and reasonably estimable.
IFRS: IAS 37, more probable than not.
Adjustment: reverse French provisions below the parent's threshold, remeasure the rest.
6. Revenue recognition
French GAAP: transfer of risks and rewards.
US GAAP and IFRS: ASC 606 and IFRS 15, five-step model on transfer of control.
Adjustment: material for long-term contracts, bundled deliverables and variable consideration. Marginal for plain sales of goods.
7. Asset measurement
French GAAP: historical cost. Revaluation of intangibles prohibited. Useful lives often aligned on tax practice.
US GAAP: historical cost.
IFRS: revaluation model available for property, plant and equipment (IAS 16).
Adjustment: revaluation differences and useful-life realignment.
8. Presentation, since the ANC 2022-06 overhaul
Regulation ANC 2022-06 applies to financial years opened from 1 January 2025.
Criteria for the exceptional result (résultat exceptionnel) redefined.
Expense-transfer technique through account 79 removed.
Financial statement models and notes reorganised.
First application is a change of method, disclosed in the notes.
This one moves balances between lines rather than changing measurement. Groups discover it late, because a mapping table built before 2025 silently breaks.
Deferred tax on every adjustment
Each adjustment above creates a temporary difference, because the French statutory accounts drive the French tax return while the group figures do not.
Deferred tax is recognised in the group accounts, not in the French statutory accounts, where its use is restricted.
Measured at the French corporate tax rate applicable on reversal.
Skipping it produces a bridge that ties on pre-tax income but not on net income or equity.
That last point is the most frequent cause of a reconciliation failing at group audit.
Eight differences, eight workpapers, every period. We run this schedule monthly or quarterly for foreign-owned French entities, deferred tax included, documented to a standard your group auditor can test.
Ask what it would cost for your entity →
What French GAAP requires beyond the numbers ?
Three obligations that have no US GAAP or IFRS equivalent, and that a group reporting package does not satisfy:
Standardised chart of accounts. Accounts follow the PCG classes: 1 equity and borrowings, 2 fixed assets, 3 inventories, 4 third parties, 5 financial accounts, 6 expenses, 7 income.
FEC (Fichier des Écritures Comptables). A structured export of all accounting entries, in French, producible on demand during a tax audit under article L47 A of the Livre des Procédures Fiscales. An English-language export from a group tool does not satisfy it.
French language and euro. Accounting documents produced to the authorities are expected in French, under article 54 of the General Tax Code.
An existing ERP can serve a French subsidiary, provided it produces the PCG chart, a compliant FEC and the prescribed statement formats. The constraint is the audit trail, not the software.
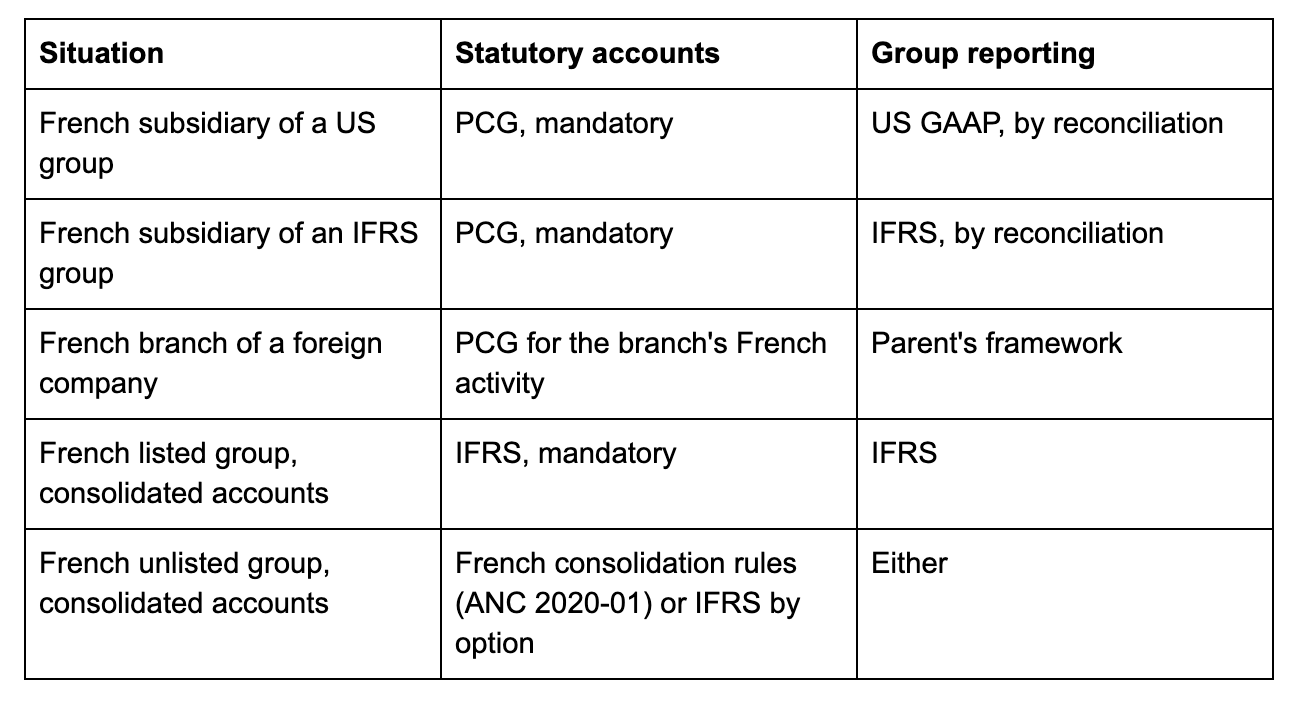
Which framework applies to your French entity ?
A French sub-group only has to consolidate once it exceeds two of three thresholds over two consecutive years. Those thresholds were raised for financial years closed from 1 January 2025, by article D. 230-2 of the Commercial Code:
Total assets above 30 million EUR, up from 24 million.
Revenue above 60 million EUR, up from 48 million.
More than 250 employees, unchanged.
Building and defending the reconciliation itself is a separate exercise, covered step by step in our mapping and financial statement reconciliation method.

AUDIT
ACCOUNTING

PAYROLL
How Vachon helps subsidiaries navigate French GAAP and US GAAP ?
Does France use GAAP or IFRS ?
Both, at different levels. Individual company accounts always follow French GAAP. Consolidated accounts follow IFRS where the group is listed on a regulated market, and either French consolidation rules (regulation ANC 2020-01) or IFRS by option where it is not. IFRS has been mandatory for listed groups in the EU since financial year 2005, under Regulation (EC) 1606/2002.
Is IFRS accepted in France for statutory accounts?
No. An IFRS-only set of accounts cannot be filed at the Registre du Commerce et des Sociétés, and it cannot support the French tax return. The obligation is on the individual accounts of the French entity, regardless of what the parent files elsewhere.
Can a French subsidiary keep its books directly in US GAAP?
No, and the exposure is practical rather than theoretical. A ledger held in US GAAP cannot produce a compliant FEC, which is the file a tax inspector requests first. Failure to produce it can lead to rejection of the accounts and reconstitution of the taxable result by the administration.
Who sets French accounting standards?
The Autorité des Normes Comptables, a public body created in 2009 by merging the Conseil National de la Comptabilité and the Comité de la Réglementation Comptable. Its regulations are approved by ministerial order and published in the Journal Officiel, which is what gives the PCG legal force.
How often does the PCG change?
The ANC amends the PCG most years. Two changes matter for current reporting: regulation ANC 2022-06, applicable to financial years opened from 1 January 2025, which reorganised the statements and the exceptional result, and the consolidated PCG version applicable from 1 January 2026.
Reviewed by
This page is maintained by the technical team of Vachon, a chartered accountancy and audit firm registered with the Ordre des Experts-Comptables de Paris Île-de-France and the Compagnie Nationale des Commissaires aux Comptes.
Founded in 1997, based at Square Louvois, 1-3 rue Lulli, 75002 Paris.
Around 40 professionals, working almost exclusively with foreign-owned French entities.
Founding member of the AICPA international council, which is uncommon for a French firm and reflects our dual-standard practice.
We prepare the French statutory accounts and the reconciliation package behind them, under partner supervision.